
Carbon & Sustainability
Sustainability Reporting
Reporting aligned to CSRD, including ESRS E4 biodiversity disclosure.
Overview
Reporting works when a reader can see what was measured, what changed and what it means. Okala supports reporting under CSRD and the ESRS, from the double materiality assessment to the disclosures themselves. Our ecologists draft ESRS E4 biodiversity and ecosystems disclosures from real data, and the same approach applies to voluntary and investor reporting.
How we approach it
We agree the framework and the audience first. Data are checked against the narrative so a figure in a table is the same figure in the text. Claims are written at the strength the evidence supports. Drafts go through the review cycles your legal, sustainability and leadership teams already use.
What we deliver
- Double materiality assessment to set which ESRS topics apply
- ESRS E4 biodiversity and ecosystems disclosures, drafted by ecologists
- Report structure aligned to the framework or audience you are writing for
- Data review so figures, boundaries and narratives match
- Drafting that separates evidence, interpretation and commitment
- Graphics and tables that can be reused in other disclosures
- Support through internal and external review
- A source file so next year's report does not start from a blank page
What you receive
You receive a report that a sceptical reader can follow from data to statement, and a record of what was left out because the evidence was not there.
When you need it
You need this when a disclosure, investor update or regulatory report has to describe environmental performance without overstating the evidence.
Related services
Carbon & ESG Advisory
Carbon strategy and ESG advice for regulated and investor contexts.
GHG Inventories
Scope 1, 2 and 3 inventories to the GHG Protocol, giving a reliable baseline for targets and disclosure.
Gap Analyses & Audits
Audits against your chosen framework, with a prioritised action plan.
TNFD Assessments
Assessments of nature-related risks, dependencies and impacts following the TNFD LEAP approach, for companies, investors and lenders.
Dashboards & Reporting Tools
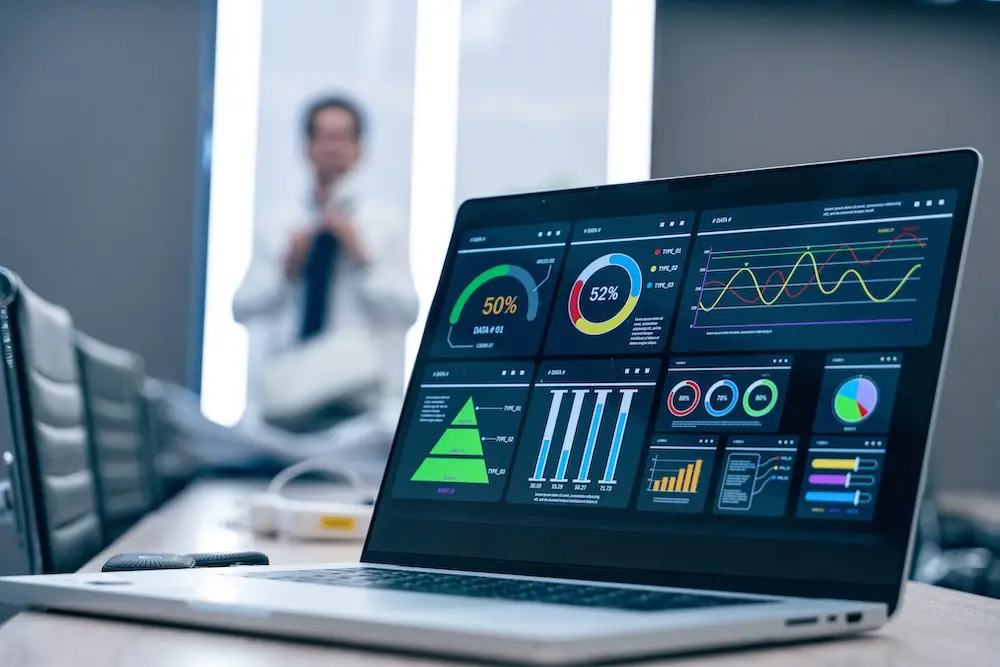
Interactive dashboards and reporting interfaces that make complex environmental data usable for teams and stakeholders.
Biodiversity Action & Management Plans
Plans and monitoring programmes that turn assessment findings into commitments you can track.